Radiology employers don't refinance your student loans in 2026 — refinancing is a private lender product, not an employee benefit. The best radiology jobs with student loan refinancing in mind are the ones that either forgive federal balances outright, hand you cash to apply toward principal, or pay enough that refinancing privately actually makes sense. Best overall for long-term debt relief: PSLF-eligible nonprofit and academic radiology jobs. Best for guaranteed cash today: radiology jobs with employer loan repayment assistance. Best for federal benefit stacking: radiology jobs at VA hospitals.
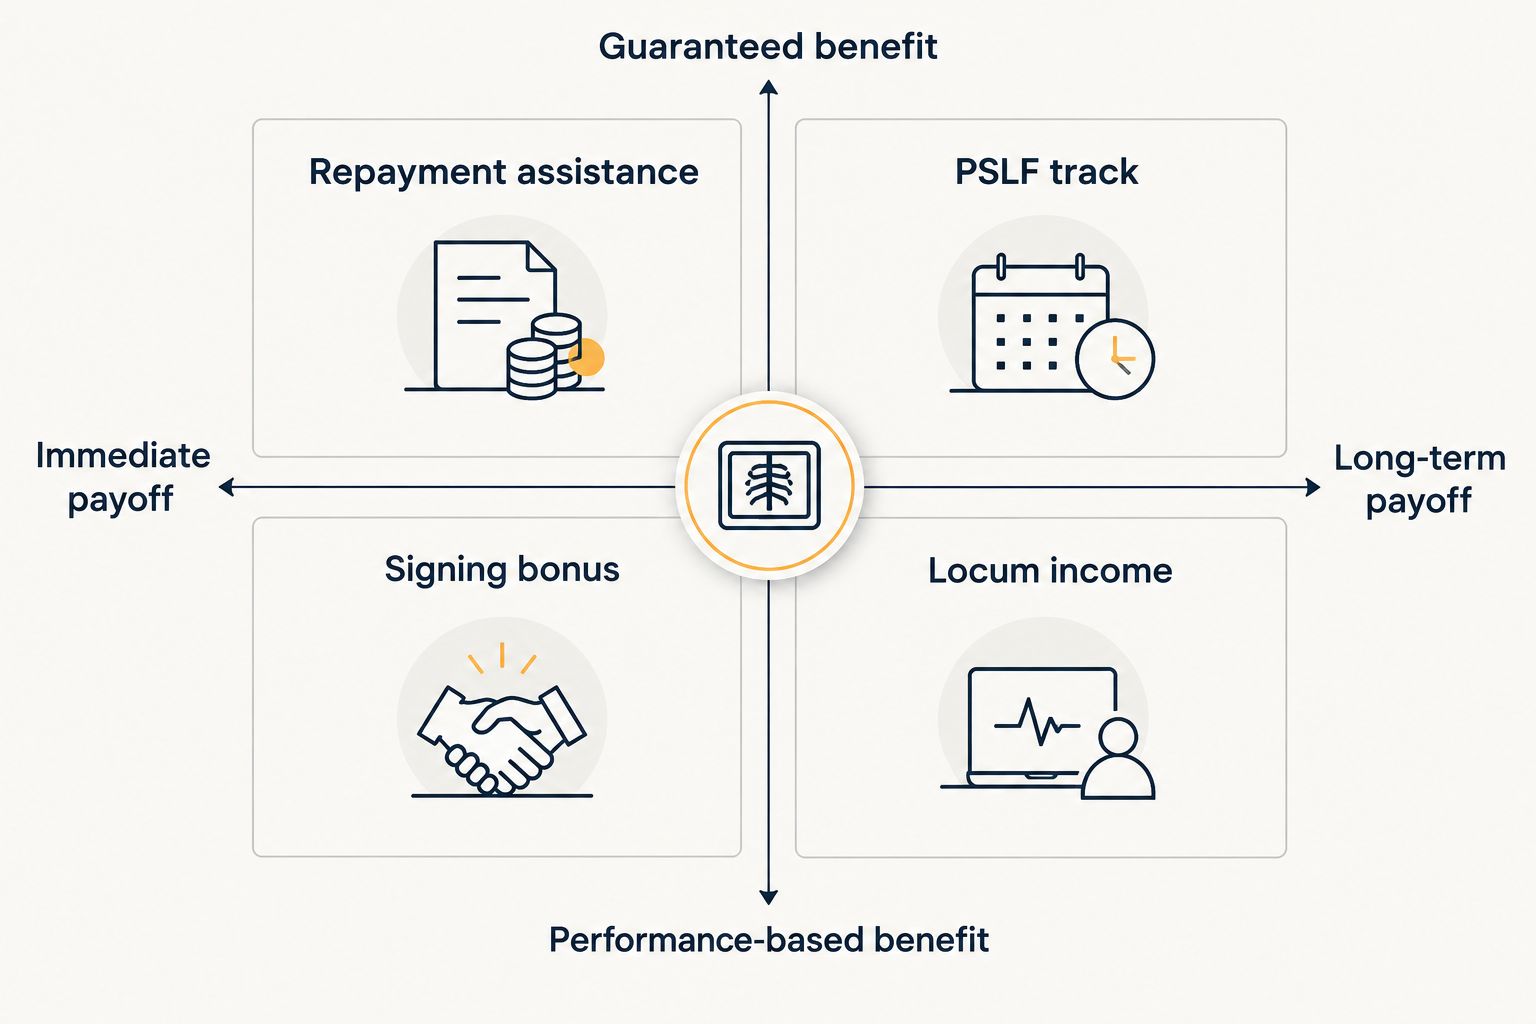
- PSLF-eligible nonprofit and academic radiology jobs cancel remaining federal balances after 120 qualifying payments — the top pick among best radiology jobs with student loan refinancing searches.
- Radiology jobs with employer loan repayment assistance apply direct annual or lump-sum contributions to existing debt.
- VA hospital radiology jobs stack federal loan repayment programs on top of a GS-scale salary.
- Locum tenens and 1099 radiology income builds the fastest private-payoff bridge before refinancing on your own terms.
- Signing bonuses in 2026 hand new radiologists lump-sum cash at start date, but taxed as ordinary income.
Why this matters
Searches for "best radiology jobs with student loan refinancing" almost always mean something narrower: which jobs make the debt easier to carry. No hospital or practice writes a check to a refinance lender on your behalf. What they can do is qualify you for federal forgiveness, contribute directly to your balance, or pay you enough that a private refinance actually lowers your rate instead of just extending your risk.
PSLF-eligible nonprofit and academic radiology jobs sit at one end of that spectrum — full forgiveness, no refinance needed. Locum tenens income sits at the other — no employer help at all, but the highest gross pay to refinance against. RadBoard aggregates more than 5,000 radiology positions from 20 sources in 2026, and filtering by employer type is the fastest way to separate the two.
What makes the best radiology job for handling student loans
- Employer tax status — nonprofit and government employers qualify for PSLF; for-profit groups do not.
- Structure of any repayment assistance — annual stipend, lump sum, or a vesting schedule that claws back unpaid amounts.
- Signing bonus size relative to base salary — a bigger bonus means more principal paid down on day one.
- Service commitment attached to any loan benefit — most repayment programs and some signing bonuses require staying 2-4 years.
- Total compensation ceiling — RVU bonuses and locum day rates determine how fast you can self-fund a payoff or refinance.
- Location-based incentive stacking — rural, VA, and underserved-area postings often combine two or three of the above.
Radiology jobs and student loan benefits at a glance
| Job category | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PSLF-track nonprofit/academic jobs | Long-term forgiveness | Remaining balance forgiven tax-free after 120 payments | 10-year commitment to a qualifying employer |
| Jobs with employer loan repayment assistance | Direct cash contributions | Money applied straight to loan principal | Usually vests over 2-4 years |
| VA hospital radiology jobs | Federal benefit stacking | Federal repayment programs plus a stable salary | GS pay scales cap total compensation |
| Locum tenens / 1099 radiology work | Fastest private payoff | Higher day rates accelerate a self-funded payoff | Zero employer-side loan benefit |
| Jobs with signing bonuses | Immediate lump sum | Cash in hand at start date | Taxed as ordinary income, sometimes clawed back |
1. PSLF-track nonprofit and academic radiology jobs: best for long-term forgiveness
Nonprofit hospitals and academic medical centers qualify as Public Service Loan Forgiveness employers under federal rules. A radiologist on an income-driven repayment plan who makes 120 qualifying monthly payments while employed full-time at one of these institutions gets the remaining federal balance forgiven, tax-free.
PSLF-track radiology jobs pros:
- Forgives the full remaining balance after 10 years, regardless of size
- Forgiven amount is not taxed as income under current federal rules
- Stackable with income-driven repayment plans that keep monthly payments manageable
PSLF-track radiology jobs cons:
- Requires a full 10-year commitment to a qualifying nonprofit or government employer
- Switching to a for-profit private practice resets the clock to zero
- Refinancing federal loans into a private loan permanently disqualifies you from PSLF
Best for: early-career radiologists comfortable with a decade at one nonprofit or academic system. Verdict: Buy.
2. Radiology jobs with employer loan repayment assistance: best for direct cash contributions
Some hospitals, especially in rural and underserved markets, pay a set amount directly toward a new hire's existing loan balance rather than routing it through a refinance. Radiology jobs with loan repayment assistance typically structure this as an annual stipend or a lump sum tied to a signing agreement.
Loan repayment assistance jobs pros:
- Contributions go straight to principal, cutting the balance you'd otherwise refinance
- Frequently paired with a separate signing bonus
- Common at facilities recruiting for hard-to-fill locations, which raises negotiating leverage
Loan repayment assistance jobs cons:
- Vesting schedules can require repayment if you leave before the term ends
- Contributions are usually taxed as ordinary income in the year received
- Total annual amount varies by employer and isn't standardized across the industry
Best for: early-career radiologists who want debt reduction now instead of a 10-year forgiveness timeline. Verdict: Buy.
3. Radiology jobs at VA hospitals: best for federal benefit stacking
VA hospital radiology jobs run federal loan repayment programs alongside a GS-scale salary, and the VA itself qualifies as a PSLF employer since it's a federal agency.
VA radiology jobs pros:
- Federal loan repayment programs run in parallel with PSLF eligibility
- Job security and predictable scheduling compared to most private practice contracts
- No non-compete or productivity-quota pressure typical of PE-backed groups
VA radiology jobs cons:
- GS pay scales cap total compensation below what private practice or locum work pays
- Credentialing and hiring timelines move slower than private-sector recruiting
Best for: radiologists who want federal stability and loan help in one package rather than piecing benefits together. Verdict: Buy.
4. Locum tenens and 1099 independent contractor radiology jobs: best for fastest private payoff
Locum and 1099 radiology work carries no employer loan benefit at all — no PSLF, no repayment assistance, no bonus. What it does offer is higher gross day-rate income, which builds the debt-to-income ratio a private lender wants to see before offering a competitive refinance rate.
Locum/1099 radiology work pros:
- Day rates run above employed base pay in most markets
- Physicians can stack multiple contracts to raise gross income further
- Stronger income and reduced debt load improve refinance terms with private lenders
Locum/1099 radiology work cons:
- Zero employer contribution toward existing loan balances
- Physicians cover their own benefits, malpractice tail, and self-employment tax
- Income is inconsistent between contracts, which complicates refinance underwriting timing
Best for: mobile radiologists building a stronger balance sheet before refinancing on their own terms. Verdict: Hold — a payoff strategy, not a loan-benefit job.
5. Radiology jobs with signing bonuses: best for immediate lump-sum cash
A signing bonus doesn't touch your loan balance directly, but it's cash in hand on day one that a radiologist can apply straight to principal or hold as a refinance down-payment equivalent.
Signing-bonus radiology jobs pros:
- Lump sum arrives at or near the start date
- Can be applied directly to loan principal ahead of any refinance decision
- Negotiable in a competitive 2026 hiring market, especially for hard-to-fill subspecialties
Signing-bonus radiology jobs cons:
- Taxed as ordinary income in the year received
- Many contracts require repayment if you leave before a set term, often 1-2 years
- A bonus alone doesn't match the multi-year value of ongoing repayment assistance
Best for: radiologists who want a supplement to another loan strategy, not a standalone one. Verdict: Buy as a supplement.
How this list was ranked
Ranking followed the criteria above in order: employer tax status first (it gates PSLF eligibility entirely), then the structure and vesting terms of any direct repayment assistance, then income ceiling for self-funded payoff strategies. Nonprofit status and federal program eligibility are matters of public record; benefit structures were cross-checked against listings aggregated across RadBoard's 20 sources in 2026.
Which radiology job should you choose for handling student loans in 2026?
If you're early in a 10-year PSLF clock and don't mind staying with one nonprofit or academic employer, staying the course beats any private refinance — forgiveness wipes out the balance refinancing would only shrink. If you want cash now, chase employer loan repayment assistance or a signing bonus first, and only refinance privately once you've confirmed your monthly cash flow genuinely improves. If you're mobile and debt-averse, locum tenens or 1099 income builds the fastest bridge to a private refinance on terms you control.
Browse radiology jobs by benefit
Search 5,000+ listings from 20 sources and filter by employer type in 2026.
FAQ
What's the best radiology job for paying off student loans in 2026?
PSLF-eligible nonprofit and academic radiology jobs give the largest total benefit since they forgive the remaining federal balance after 120 qualifying payments. Employer loan repayment assistance is the best option for cash sooner rather than later.
Do any radiology employers refinance student loans directly?
No radiology employer refinances loans directly in 2026 — refinancing is a private lender product. Employers instead offer forgiveness eligibility, repayment assistance, or income high enough to make refinancing worthwhile.
Is PSLF better than refinancing for radiologists?
For radiologists with federal loans and a stable nonprofit or government job, PSLF usually beats refinancing because it forgives the entire remaining balance tax-free. Refinancing into a private loan permanently disqualifies you from PSLF.
How long does PSLF forgiveness take for a radiologist?
PSLF requires 120 qualifying monthly payments, roughly 10 years, while working full-time for a qualifying nonprofit or government employer. The clock resets if you switch to a for-profit employer during that period.
Do VA hospital radiology jobs help with student loans?
Yes, VA hospital radiology jobs carry federal loan repayment programs and the VA also qualifies as a PSLF employer since it's a federal agency. Pay is capped at GS scales in exchange for those benefits.
Can locum tenens radiology work pay off loans faster?
Locum tenens and 1099 radiology work typically pays higher day rates than employed positions, which builds gross income faster for a self-funded payoff or a stronger private refinance application. There's no employer loan benefit attached to this work.
Are radiology signing bonuses taxed the same as regular salary?
Yes, signing bonuses are taxed as ordinary income in the year they're received. Some contracts also require repaying the bonus if you leave before a set term, often 1 to 2 years.
Does refinancing federal loans mean losing PSLF eligibility?
Yes, refinancing federal student loans into a private loan permanently removes PSLF and income-driven repayment eligibility. That decision can't be reversed, so it's worth confirming your employer's PSLF status before refinancing.
One last thing
The irreversible part of this decision gets skipped most often: refinancing a federal loan into a private one permanently kills PSLF and income-driven repayment eligibility, even if you later take a nonprofit job that would have qualified. Confirm your current or target employer's nonprofit status before touching a federal loan in 2026 — that single check determines which half of this list even applies to you.