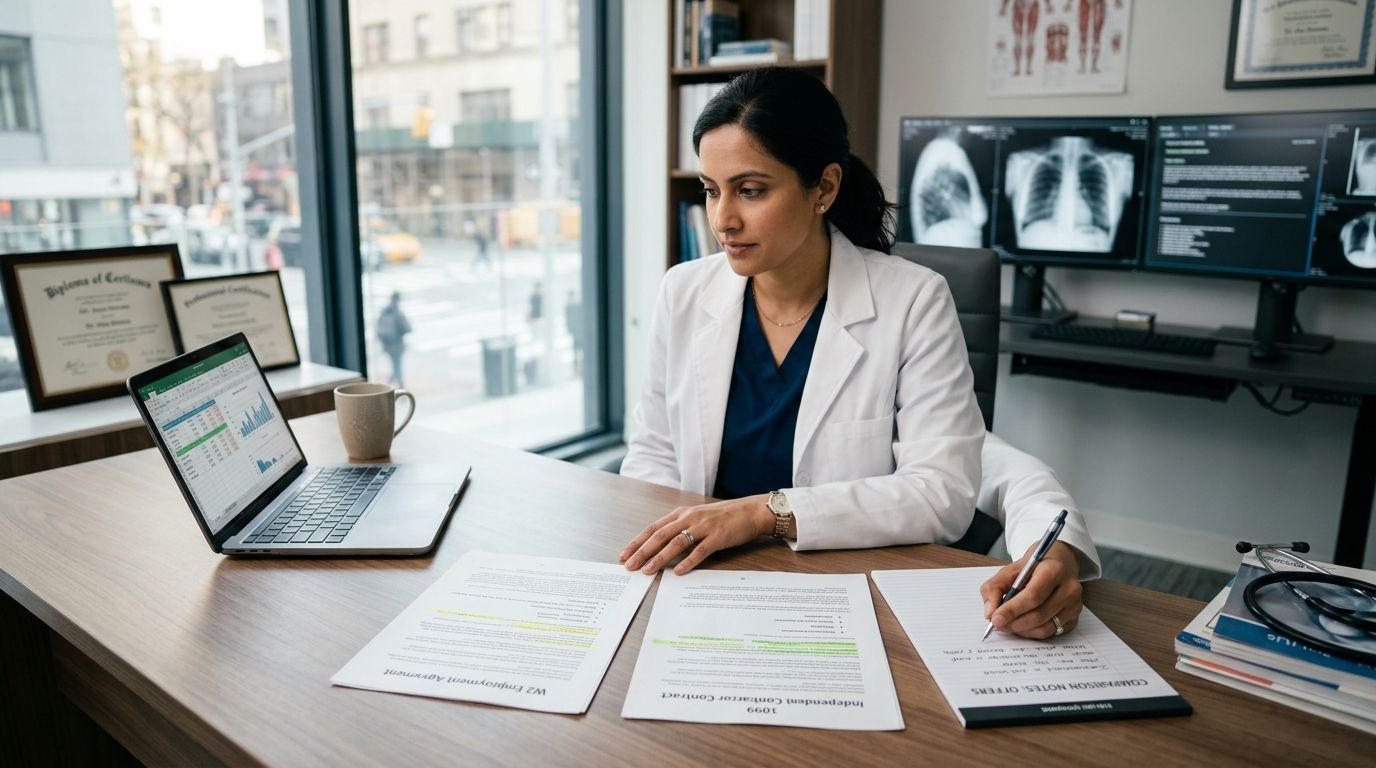
Comparing a W2 radiology offer to a 1099 offer only works when you convert both to the same after-tax, after-expense number per year — not when you stack the two headline salary figures side by side. The gross rate on a 1099 contract is revenue, not pay.
- W2 vs 1099 radiology jobs need side-by-side conversion to after-tax, after-expense pay — headline salary alone misleads.
- 1099 radiologists owe the full 15.3% self-employment tax; W2 employees have 7.65% withheld and the employer matches the rest.
- 1099 offers must absorb self-funded health insurance, retirement contributions, and malpractice tail before comparison.
- W2 jobs bundle benefits and tail coverage into the offer; 1099 jobs pay a rate premium because you fund those yourself.
- RadBoard aggregates 5,000+ radiology jobs from 20 sources, listing both pay structures side by side.
Why this matters
Radiology offers in 2026 mix W2 hospital-employed roles with 1099 contract and locum positions, and the two pay structures are not interchangeable on paper. A recruiter quoting a 1099 day rate is quoting gross revenue — every payroll tax, benefit, and insurance line an employer normally absorbs becomes your line item instead.
Skipping the conversion is the most common reason a radiologist takes a 1099 job expecting a raise and nets less than the W2 position they left. RadBoard aggregates listings from 20 sources across both structures, so the comparison framework has to be the same every time.
How to compare W2 vs 1099 radiology job offers side by side
Build one table with both offers and run every line through it before comparing final numbers. These are the categories that consistently separate the two structures in 2026.
| Factor | W2 | 1099 |
|---|---|---|
| Payroll tax | 7.65% withheld, employer matches 7.65% | Full 15.3% self-employment tax up to the Social Security wage base, then 2.9% Medicare |
| Health insurance | Employer-subsidized | Self-funded or individual market |
| Retirement | 401(k)/403(b), often with employer match | SEP-IRA or solo 401(k), no match |
| Malpractice | Employer-carried, tail often included | Negotiated per contract, tail frequently excluded |
| Paid time off | Accrued and built into salary | Unpaid — every day off is zero revenue |
| Business deductions | Limited | Home office, CME, travel, equipment deductible |
| Best for | Radiologists who want predictable net income with benefits bundled in | Radiologists whose rate premium clears tax, benefits and tail costs |
A W2 radiology job wins on predictability; a 1099 radiology job only wins on net income when the rate clears self-employment tax, self-funded benefits and malpractice tail with room to spare.
Once the table exists, comparing radiology job offers beyond base salary becomes arithmetic instead of guesswork.
W2 radiology jobs: what the salary already covers
A W2 offer folds most of the cost categories above into employer overhead, which is exactly why the base salary reads lower than an equivalent 1099 rate.
- Payroll tax is split: you pay 7.65%, the employer pays 7.65%, withheld automatically each pay period.
- Health, dental, and often disability coverage are subsidized or fully covered.
- A 401(k) or 403(b) frequently carries an employer match — money invisible in a salary-only comparison.
- Malpractice insurance, and usually the tail, sits with the employer.
- Paid time off is inside the salary, so a week away costs nothing in lost pay.
Pros: predictable monthly income, automatic tax withholding, benefits and coverage handled for you, easier mortgage and loan underwriting.
Cons: lower headline pay, minimal business deductions, schedule set by the employer, and the group controls your case mix.
Verdict: Buy the W2 structure when stable net income and bundled benefits matter more than maximizing gross annual pay.
1099 radiology jobs: what the rate has to cover
A 1099 contract pays a higher gross rate precisely because nothing above is included. You are pricing your own benefits and taxes into the number you negotiate.
- You owe the full 15.3% self-employment tax on net earnings to the Social Security wage base, then 2.9% Medicare above it, with no employer covering half.
- Health insurance is self-funded, and the premium comes straight out of contract revenue.
- Retirement runs through a SEP-IRA or solo 401(k) you fund entirely, though the contribution ceiling can beat a typical employer plan.
- Malpractice — including tail — is a negotiated line item. Some 1099 radiology roles include it. Most do not.
- Every unpaid day, sick or vacation, is a direct revenue hit with no salary floor underneath.
Pros: higher gross rate, real business deductions, schedule and assignment control, ability to stack contracts across states.
Cons: full self-employment tax burden, quarterly estimated payments, no paid leave, benefits and tail entirely on you, income varies with volume.
Verdict: Buy the 1099 structure only after modeling tax, benefits and tail against the quoted rate — if those costs eat the premium, the W2 offer nets more.
For radiologists already leaning contract-side, 1099 independent contractor radiology jobs covers which practice types structure roles this way.
Compare W2 and 1099 listings now
Search 5,000+ radiology jobs from 20 sources with AI-powered search and swipe-to-save.
Why the W2 vs 1099 gap varies
The spread between comparable W2 and 1099 radiology offers moves with these factors:
- Subspecialty demand — high-demand reads such as neuro, IR and breast MRI carry larger 1099 rate premiums because the practice needs coverage regardless of structure.
- Geographic market — shortage states push 1099 day rates up faster than W2 salaries, since contract staffing plugs gaps quickly.
- Contract length — short-term locum work commands a higher effective rate than a standing 1099 arrangement, because there is no continuity guarantee.
- Malpractice tail structure — whether tail is included, prorated, or fully yours swings the true cost of a 1099 contract more than any other single line.
- Multi-state tax exposure — self-employed radiologists reading across states face heavier filing complexity and accounting cost than single-state W2 employees.
- Benefits replacement cost — a radiologist covered by a spouse's employer health plan needs far less rate premium than one buying individual coverage outright.
“A 1099 day rate is gross revenue, not take-home pay — the difference is every benefit your last employer quietly paid for.”
Is W2 or 1099 better for radiologists in 2026?
Neither is universally better in 2026. A W2 radiology job wins when predictable net pay and bundled benefits matter most; a 1099 job wins only when the quoted rate clears self-employment tax, self-funded insurance and malpractice tail. Run both through one after-tax model, because a rate that looks materially higher on paper can land close to even once those costs come out.
How much higher should a 1099 radiology rate be than a W2 salary?
High enough to cover the full 15.3% self-employment tax exposure, self-funded health insurance, unmatched retirement contributions, and any malpractice tail the contract excludes. There is no fixed percentage — each of those items varies by state, family coverage situation and subspecialty, which is why the side-by-side table beats any rule of thumb.
Can a radiologist switch between W2 and 1099 mid-career?
Yes, and it's common in 2026 — typically around fellowship completion, relocation, or a move toward locum work. The tax and benefits setup resets at every switch, so the same comparison applies each time rather than once at the start of a career.
FAQ
What's the main difference between W2 and 1099 radiology jobs?
A W2 radiology job withholds payroll tax and bundles benefits and malpractice coverage into the salary. A 1099 job pays a higher gross rate and leaves self-employment tax, insurance and malpractice tail to the radiologist.
Do 1099 radiologists pay more tax than W2 radiologists?
1099 radiologists owe the full 15.3% self-employment tax on eligible net earnings versus the 7.65% withheld from a W2 paycheck. 1099 status also opens business deductions that W2 employees cannot claim.
Is malpractice tail coverage included in 1099 radiology contracts?
Usually not. Some 1099 radiology contracts include tail, most leave it to the physician, so confirm the terms in writing before treating the rate as comparable to a W2 offer.
Can I negotiate benefits into a 1099 radiology contract?
You negotiate a higher rate to offset self-funded benefits rather than the benefits themselves. 1099 contracts do not typically carry employer-style health insurance or retirement matching.
Which pays more, W2 or 1099 radiology work?
1099 work pays a higher gross rate, but after self-employment tax, self-funded benefits and malpractice costs, the net gap to a comparable W2 salary can shrink sharply or reverse.
How do I calculate take-home pay from a 1099 radiology offer?
Subtract self-employment tax, health insurance premiums, retirement contributions and malpractice costs from gross contract revenue, then compare that net figure against the W2 offer's after-tax salary.
Do 1099 radiologists have to pay quarterly estimated taxes?
Yes. Without employer withholding, 1099 radiologists make quarterly estimated payments, which changes cash flow timing compared with a W2 paycheck.
Is locum tenens radiology always 1099?
Most locum tenens radiology work is structured as 1099, though some staffing arrangements are W2. Confirm the classification in the contract, since it determines who covers tax, benefits and malpractice.
One last thing
The line radiologists overlook most often is not the tax rate — it's the malpractice tail. A 1099 contract that stays silent on tail can produce a bill the moment the assignment ends, and that single item has flipped plenty of "better paying" 1099 offers into the worse deal after the fact. Get tail terms in writing before you sign, not verbally confirmed by a recruiter in 2026.