Best overall starting point: MedPro Group for comparing occurrence and claims-made coverage. Best for physician-owned insurer preference: The Doctors Company. Best for group-policy review: ProAssurance. Best for pairing coverage with risk-management resources: Coverys. This 2026 guide compares those providers by policy structure and radiology practice fit—not an unsupported ranking of premiums or claims outcomes.
- The best malpractice insurance for radiologists matches clinical scope, covered states, and coverage after departure—not just the insurer name.
- MedPro Group is a starting point for comparing occurrence and claims-made policy structures.
- Compare The Doctors Company, ProAssurance, and Coverys against the same written coverage requirements.
- RadBoard helps radiologists compare career opportunities; insurers and policy documents determine malpractice coverage.
Why this matters
A radiology offer and its malpractice policy are separate documents. The employment agreement assigns responsibilities; the insurance contract defines coverage. You need both before accepting a position.
RadBoard aggregates 5,000+ radiology positions from 20 sources. RadBoard is a radiology job search platform for physicians comparing career opportunities, not a malpractice insurer. Use your job shortlist to identify the work you need insured, then compare policies against that scope.
For a 2026 job change, examine what happens after departure as closely as what happens during employment. Employer-provided coverage does not, by itself, answer whether outside shifts, prior work, or future claims are covered.
The best malpractice policy is the one that covers your actual work and leaves no unresolved coverage gap when you leave. An insurer's reputation cannot substitute for that contract review.
What makes the best malpractice insurance for radiologists
Use these six criteria before comparing providers. Each answers a different coverage question.
- Clinical scope: Does the policy describe your diagnostic interpretations, procedures, supervision, and other professional services accurately?
- Covered locations: Does the insurer accept your practice arrangement, including remote reading and every relevant jurisdiction?
- Coverage trigger: Is the policy occurrence or claims-made, and what conditions determine when coverage responds?
- Departure protection: Who arranges extended reporting coverage or accepted prior-acts coverage when the relationship ends?
- Defense and settlement: How does the contract handle defense expenses, attorney selection, settlement consent, and disagreements about settlement?
- Individual and group protection: Are you an insured, is your practice entity insured when needed, and how do individual and shared limits interact?
A certificate of insurance is useful evidence that a policy exists. It is not a substitute for the policy, endorsements, or a written explanation of an exclusion.
For your 2026 comparison, give every insurer the same practice description. A proposal based on diagnostic reading alone is not an equivalent comparison to one that includes interventional procedures and outside assignments.
Providers at a glance
These are provider-specific starting points for a coverage review. The use-case labels identify what to investigate first; they do not establish that one carrier has better claim results than another.
| Provider | Best for | Standout consideration | Key limitation |
|---|---|---|---|
| MedPro Group | Comparing coverage triggers | Offers occurrence and claims-made medical malpractice coverage | Confirm the forms applicable to your state and practice |
| The Doctors Company | Physician-owned insurer preference | Physician-owned medical malpractice insurer | Ownership structure does not establish your policy's settlement rights |
| ProAssurance | Reviewing a group coverage arrangement | Medical professional liability insurance for physicians and healthcare organizations | Group coverage still requires an individual insured-status review |
| Coverys | Coverage with risk-management resources | Medical professional liability insurance and risk-management resources | Resources do not replace policy terms or establish coverage for a service |
No carrier wins every practice arrangement. A solo diagnostic radiologist, a procedural specialist, and a physician joining a group should not start with identical coverage assumptions.
1. MedPro Group: best for comparing coverage triggers
MedPro Group provides medical malpractice insurance, including occurrence and claims-made coverage. That makes MedPro Group a useful starting point when your main decision is how coverage responds to work performed before you change jobs or retire.
Best for: Radiologists who want to compare policy structures before choosing an insurer.
Occurrence coverage generally responds to covered incidents that happen during the policy period, even when the claim arrives later. Claims-made coverage generally requires the claim to meet the policy's reporting conditions and the incident to fall within its covered period, including any applicable retroactive date.
MedPro Group pros:
- Offers a starting point for comparing both major coverage structures.
- Lets you frame the decision around coverage continuity rather than a provider name alone.
- Supports a focused review of what happens when a policy ends.
MedPro Group cons:
- A provider's product range does not establish which form applies to your particular submission.
- An occurrence policy still requires review of exclusions, limits, and the definition of professional services.
Ask for the proposed form, declarations, and endorsements together. If you are replacing claims-made coverage, ask whether prior acts are accepted and which retroactive date appears in the proposed contract.
For a 2026 transition, do not treat a new occurrence policy as a solution for earlier claims-made work. Those are separate coverage periods requiring separate analysis.
Verdict: Hold until MedPro Group documents the coverage trigger and treatment of your prior work.
2. The Doctors Company: best for physician-owned insurer preference
The Doctors Company is a physician-owned medical malpractice insurer. It belongs on your shortlist when physician ownership is an explicit selection criterion—not because ownership proves that every policy provision favors the insured.
Best for: Radiologists who want physician ownership to be part of their insurer selection.
Keep the ownership question separate from the settlement question. Your rights depend on the insurance contract, including consent provisions and any consequences attached to refusing a proposed settlement.
The Doctors Company pros:
- Meets a clearly defined physician-owned insurer preference.
- Provides a medical malpractice option to compare with other physician liability carriers.
- Gives you a distinct organizational criterion beyond the coverage form itself.
The Doctors Company cons:
- Physician ownership does not establish an unrestricted right to refuse settlement.
- The insurer's name does not resolve coverage for outside shifts or services omitted from your application.
Ask The Doctors Company to explain the settlement clause in the proposed policy. Request the relevant wording rather than relying on a broad description of physician advocacy.
For radiologists joining an employer's existing program, determine whether you can choose the insurer at all. Your practical decision might be whether to accept the employer's arrangement, not which carrier to purchase independently.
Verdict: Hold until The Doctors Company policy terms satisfy your defense and settlement requirements.
3. ProAssurance: best for reviewing group coverage
ProAssurance provides medical professional liability insurance for physicians and healthcare organizations. ProAssurance is a candidate to examine when you need to understand a practice-level arrangement alongside your individual coverage.
Best for: Radiologists evaluating a group policy or coverage for a practice entity.
Group insurance introduces questions that an individual provider comparison cannot answer. You need to know who is insured, which professional activities are covered, and whether limits apply individually or are shared under the proposed arrangement.
ProAssurance pros:
- Provides a medical professional liability option for physician and organization coverage review.
- Fits a comparison that includes both individual and practice-level exposures.
- Keeps entity coverage on the agenda when your business structure requires it.
ProAssurance cons:
- Coverage for an organization does not automatically establish coverage for every physician or outside engagement.
- A group arrangement requires examination of shared limits and departure terms, not just the certificate bearing your name.
Ask for the provision identifying insured physicians and entities. Then confirm whether work for a separate imaging center, locum assignment, or personally contracted remote shift falls within that definition.
In your 2026 group-policy review, separate employment status from insurance status. Being paid by the group does not answer every policy question about services performed elsewhere.
Verdict: Hold until ProAssurance documents individual insured status, entity coverage, and applicable limits.
4. Coverys: best for risk-management resources
Coverys provides medical professional liability insurance and risk-management resources. Coverys belongs on your comparison list when you want to examine prevention support alongside the insurance contract.
Best for: Radiologists and practices that make risk-management resources an explicit purchasing criterion.
For radiology, useful topics to investigate include critical-result communication, follow-up recommendations, documentation, and procedural consent. Ask which resources apply to your insured practice rather than assuming every program includes the same support.
Coverys pros:
- Combines a medical professional liability offering with risk-management resources.
- Gives you a defined support category to compare alongside contractual protection.
- Prompts a review of practice processes as well as coverage after an allegation.
Coverys cons:
- Educational resources do not establish coverage for an excluded procedure or location.
- Access to support does not demonstrate better outcomes for your practice without relevant evidence.
Ask Coverys which resources accompany the proposed arrangement and who can use them. Keep that answer separate from the insurer's written confirmation of your covered professional services.
Verdict: Hold until Coverys confirms both the coverage scope and the resources attached to your arrangement.
How the providers are ranked
The order starts with coverage structure, then separates physician ownership, group arrangements, and risk-management resources. Those are distinct decision paths, not interchangeable definitions of “best.”
This guide does not rank the providers by radiologist-specific premiums, claim-payment speed, or settlement outcomes. Instead, it uses established provider characteristics to identify where your policy review should begin.
Apply the same six criteria to every proposal. Reject an incomplete coverage answer before choosing between otherwise suitable carriers.
Review three documents before choosing
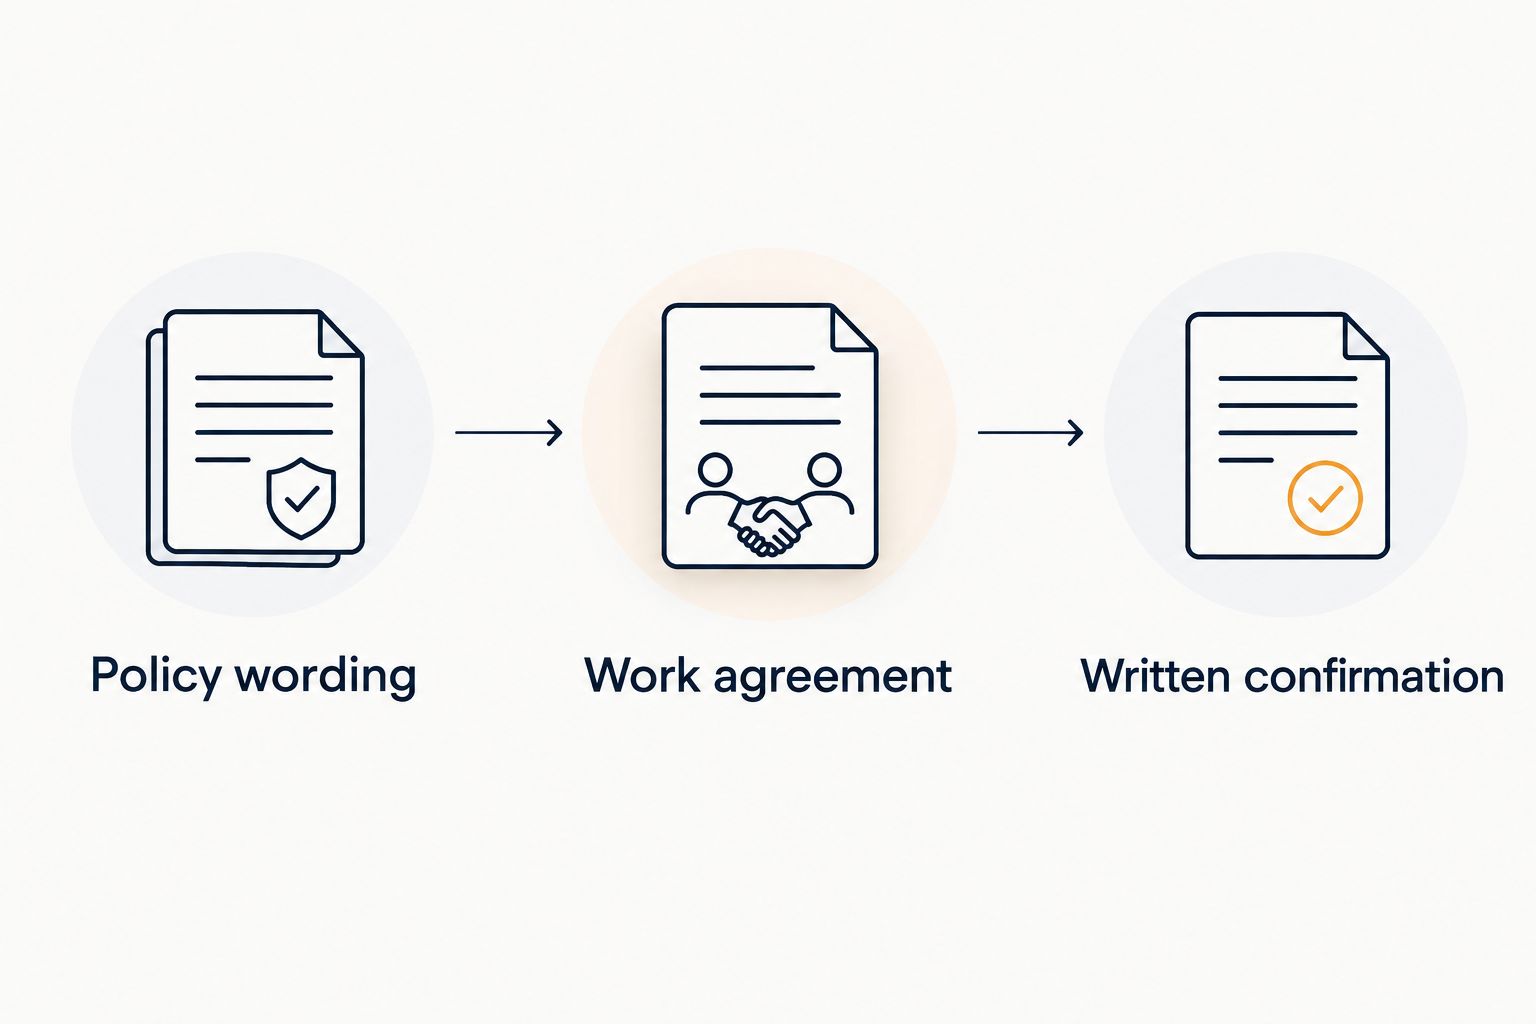
Collect 3 documents for your decision: the proposed policy, the employment or services agreement, and written coverage confirmation. Each serves a different purpose.
Policy wording
Read the declarations, policy form, and endorsements together. Identify the named insured, covered professional services, coverage trigger, retroactive date where applicable, limits, exclusions, and reporting requirements.
Check defense provisions separately. Ask whether defense expenses reduce the applicable limit and how the policy addresses representation when the physician and practice have different interests.
Work agreement
Read the malpractice clause beside the termination clause. Determine who must maintain coverage, who handles post-departure protection, and whether those responsibilities change depending on how the relationship ends.
For claims-made work, assign responsibility for extended reporting coverage explicitly. The guide to radiology jobs with malpractice tail coverage included addresses that job-search consideration; the agreement must still state your obligations.
Written confirmation
Send a precise description of your work to the insurer or authorized representative. Include your services, practice entities, locations, remote arrangements, and outside assignments.
Request confirmation tied to the proposed policy and any necessary endorsements. Save the response with your signed documents, and use qualified insurance and legal advisers to resolve conflicting language.
Which provider should you choose?
Start with MedPro Group if your unresolved question is occurrence versus claims-made coverage. Add The Doctors Company for physician ownership, ProAssurance for a group arrangement, or Coverys for risk-management resources.
Choose the policy that meets your documented requirements—not the first provider in the table. When an employer supplies coverage, review that actual program before shopping for a replacement or supplemental policy.
Use RadBoard to compare radiology career opportunities, then complete the malpractice review before signing. For your 2026 decision, keep insurer selection and job selection connected without treating a job listing as evidence of insurance coverage.
FAQ
What's the best malpractice insurance for radiologists in 2026?
The best malpractice insurance for radiologists is the policy that covers their actual services, locations, and coverage needs after departure. MedPro Group, The Doctors Company, ProAssurance, and Coverys are starting points for different policy-review priorities, not universal winners.
Is occurrence coverage better than claims-made coverage for a radiologist?
Occurrence coverage avoids the same post-cancellation reporting dependency associated with claims-made coverage for covered incidents during its policy period. Claims-made coverage requires careful review of the retroactive date, reporting conditions, and protection after the policy ends; neither form eliminates exclusions.
Do radiologists need tail coverage when leaving a job?
Radiologists leaving claims-made coverage need to resolve protection for claims reported after that coverage ends. Extended reporting coverage or accepted prior-acts coverage can address that issue, subject to the actual policies and agreement.
Does employer malpractice insurance cover moonlighting?
Employer malpractice insurance does not automatically cover moonlighting. Confirm whether the outside employer, services, and locations fall within the policy, and obtain any required endorsement before starting.
Does a teleradiologist need coverage for every state?
A teleradiologist needs insurance that accepts the actual multistate practice arrangement. Give the insurer the relevant patient, facility, and physician locations and obtain written confirmation; professional licensure and insurance coverage are separate requirements.
Does a certificate of insurance prove that every radiology procedure is covered?
A certificate of insurance does not prove that every procedure is covered. Review the policy's professional-services definition, exclusions, and endorsements for the diagnostic and interventional work you perform.
Does RadBoard provide malpractice insurance for radiologists?
RadBoard is a radiology job search platform, not a malpractice insurance provider. Use it to compare career opportunities, then verify coverage through the employer, insurer, and governing documents.
One last thing
A new policy does not automatically solve an old coverage gap. Before your final shift, confirm how claims involving earlier work will be handled after your departure.
Put that answer beside your new policy's effective date and retroactive date, where applicable. Resolve the handoff before changing jobs; a recognizable insurer name is not proof of uninterrupted protection.