PSLF saves a radiologist the eligible federal loan balance remaining after 120 qualifying monthly payments—not a fixed amount tied to specialty or hospital salary. For a 2026 job decision, calculate that projected balance and compare the repayment path with your alternatives; a nonprofit hospital address alone does not establish eligibility. Required payments and any compensation you give up to stay in qualifying employment reduce the financial advantage.
- How much does PSLF save a radiologist? The eligible balance remaining after 120 qualifying monthly payments.
- Federal Student Aid bases PSLF employment eligibility on the employer, not the hospital where you read studies.
- Compare loan payments and after-tax compensation across job offers, not forgiveness alone.
- RadBoard helps radiologists compare job opportunities; employer eligibility still requires separate verification.
How much does PSLF save a radiologist at a nonprofit hospital?
PSLF forgives the remaining eligible Direct Loan principal and interest after you meet the program requirements. There is no radiologist-specific forgiveness amount. Your loan balance, repayment history, future payments, and qualifying employment determine the result.
When reviewing radiology jobs with PSLF loan forgiveness at nonprofit hospitals, separate the advertised workplace from the legal employer. That distinction determines whether a promising position supports your repayment plan.
Use this sequence to estimate your benefit:
- Confirm eligible loans. Identify which balances are Direct Loans and which require further review. Private student loans do not qualify for PSLF.
- Confirm credited payments. Use the payment count recorded in your federal student aid account, not elapsed time since graduation.
- Project remaining payments. Estimate required payments under an available PSLF-qualifying repayment plan using your expected income and household circumstances.
- Project the remaining balance. Include interest and the effect of those payments through the expected forgiveness date.
- Compare employment paths. Evaluate total loan payments alongside after-tax earnings, benefits, and working conditions over the same period.
The projected remaining balance is your potential forgiveness amount. The difference between competing repayment and employment paths is your potential economic benefit. Those are different calculations.
Why this matters when comparing radiology offers
A loan benefit belongs in your offer comparison, but it does not replace the comparison. A position with qualifying employment still needs an acceptable call schedule, case mix, compensation structure, and workload.
For your 2026 analysis, keep two worksheets: one for the loans and another for employment compensation. Combining everything into a single headline number hides assumptions about income, payment eligibility, and how long you will stay.
RadBoard is best for radiologists comparing career opportunities across multiple job sources. Its radiology job search platform aggregates 5,000+ positions from 20 sources, but a listing is not proof that the employing entity qualifies for PSLF.
What actually determines your PSLF forgiveness amount?
Your current balance is the starting point, not the answer. Payments and interest change that balance before forgiveness, and the timing of your income changes affects the projection.
Federal Student Aid's published PSLF guidance establishes the core requirements: eligible Direct Loans, qualifying repayment, qualifying full-time employment, and 120 qualifying monthly payments. Use that guidance and your federal loan records when building a 2026 estimate; an employment advertisement cannot establish your individual eligibility.
| Calculation component | What to record | Why it matters |
|---|---|---|
| Eligible debt | Direct Loan principal and accrued interest | Only eligible debt enters the PSLF projection |
| Credited progress | Recorded qualifying payment count | Determines how much qualifying repayment remains |
| Future payments | Required payments under a qualifying plan | Reduces the balance available for forgiveness |
| Future interest | Interest under the applicable loan and repayment terms | Changes the projected ending balance |
| Employment continuity | Expected qualifying employment periods | Affects when you reach forgiveness |
| Alternative path | Payments and compensation under another job offer | Establishes whether pursuing PSLF improves your finances |
Do not count the same benefit twice. If you compare total loan payments under two repayment paths, do not then add the entire forgiven balance as another independent saving. The payment comparison already captures the debt you avoid repaying.
Which radiology employment arrangements support PSLF?
The employer matters more than the reading location. A radiologist working inside a nonprofit hospital does not automatically have qualifying employment if a separate for-profit practice employs the physician.
Federal Student Aid generally recognizes government employers and qualifying nonprofit employers, including qualifying 501(c)(3) organizations. Its guidance also describes a narrow exception for certain contracted employment when applicable state law prevents direct employment; do not assume every hospital contractor meets that exception.
| Employment arrangement | Best for | Advantage | Limitation |
|---|---|---|---|
| Direct employment by a qualifying nonprofit | Physicians seeking a nonprofit career with PSLF | Provides an identifiable employer for certification | Loan, repayment, and full-time requirements still apply |
| Direct government employment | Physicians considering public-service careers | Government employment is a recognized qualifying category | The specific role must fit your career and repayment requirements |
| For-profit group covering a nonprofit hospital | Physicians evaluating private-group work | Offers another employment path to compare | Hospital nonprofit status alone does not make the job eligible |
| Contracted work under the state-law exception | Physicians whose arrangement meets the exception | Provides a defined exception to the general employment rule | Requires verification of the actual legal and employment circumstances |
These are eligibility distinctions, not a ranking of radiology careers. A nonqualifying private-practice position deserves a full financial comparison rather than automatic rejection.
What should you ask the recruiter?
Ask for the legal employing entity, its employer identification number, and the person authorized to certify employment. Confirm whether the entity signing your employment agreement is the same entity being presented as PSLF-eligible.
If the recruiter points only to the hospital's nonprofit status, repeat the question about your employer. Ask for clarification before treating forgiveness as part of the offer's financial value.
Why PSLF savings vary between radiologists
Radiologists with similar debt balances do not necessarily receive similar forgiveness. Your repayment history and future employment path matter alongside the amount borrowed.
- Eligible starting balance. Private loans and other ineligible debt do not become PSLF-eligible because you accept a nonprofit job.
- Certified training payments. Qualifying payments during residency or fellowship reduce the qualifying repayment still required after training.
- Attending income. Income-driven payments respond to income under the applicable plan's rules, changing the projected remaining balance.
- Household circumstances. Family size and treatment of spousal income depend on the repayment plan and tax circumstances.
- Employment continuity. Nonqualifying work can extend the calendar time needed to complete qualifying payments.
- Additional principal payments. Paying more toward eligible debt reduces the balance remaining for forgiveness; evaluate that choice against your repayment objective.
For a 2026 estimate, document the assumptions behind each factor. A projection that assumes uninterrupted qualifying employment is not interchangeable with one that includes a move into nonqualifying practice.
How do you verify PSLF before signing a radiology contract?
Complete the eligibility check before assigning forgiveness value to an offer. A recruiter's statement is useful background, but your loan records and employment documentation need to support the decision.
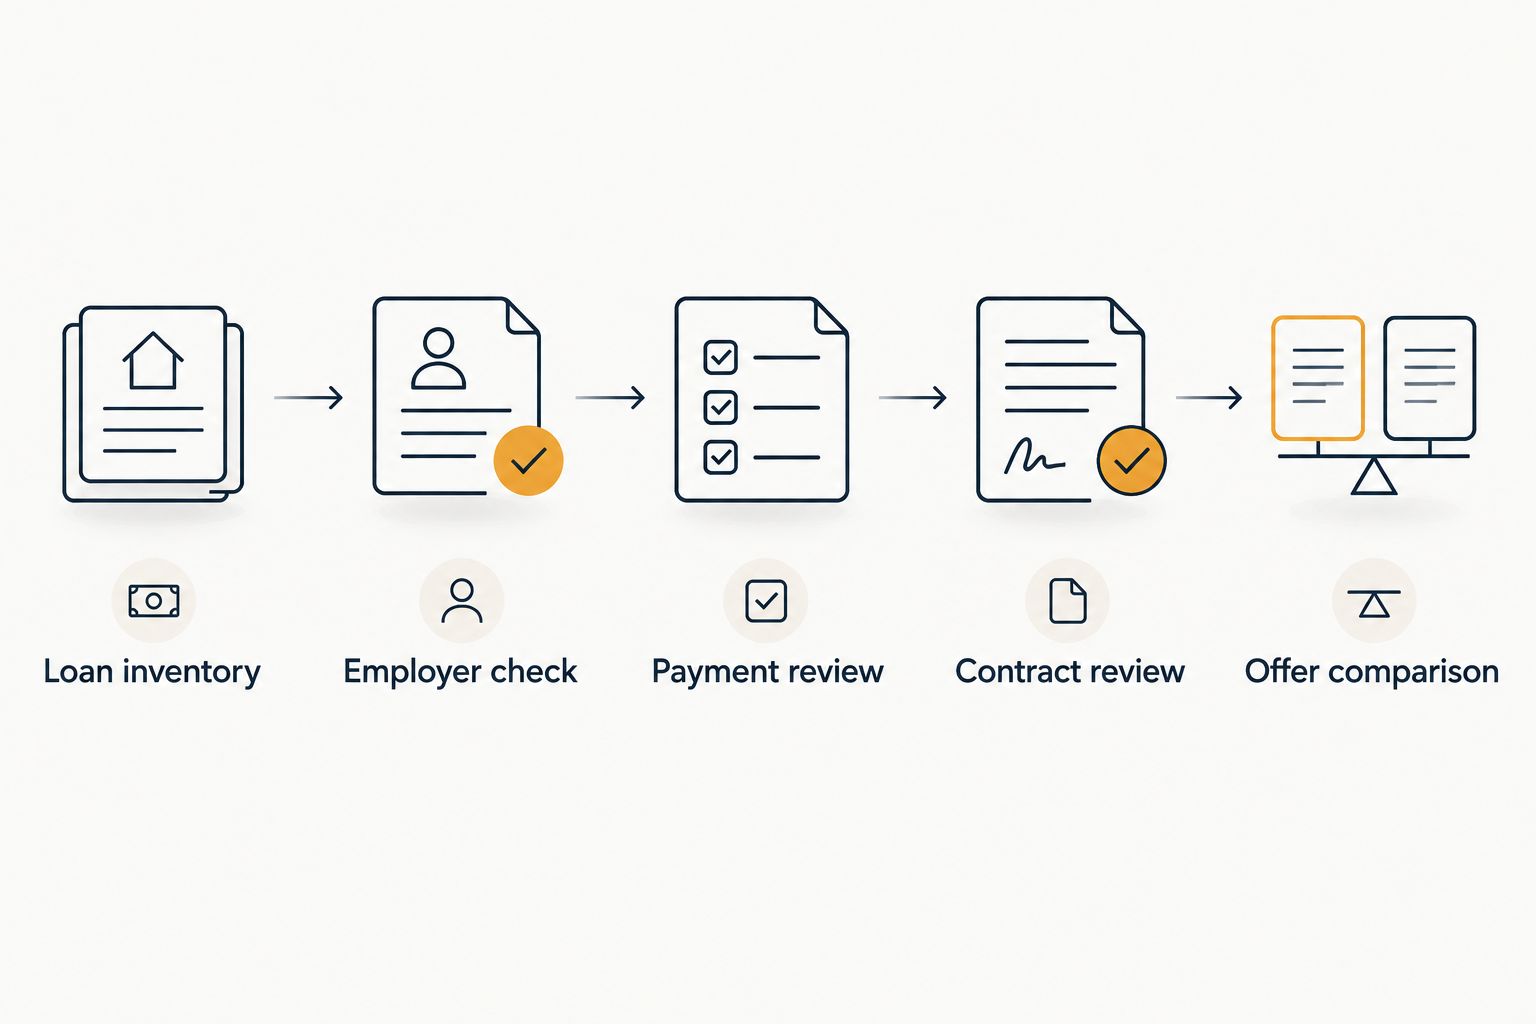
- Loan inventory. List each loan's type, balance, repayment status, and recorded qualifying payment count. Keep private loans separate.
- Employer check. Use Federal Student Aid's PSLF Employer Search and the prospective employer's identification number. Investigate unresolved or unclear results.
- Payment review. Confirm your repayment plan qualifies and examine which past months are credited. Resolve discrepancies rather than assuming they will disappear.
- Contract review. Check the employing entity, work hours, and any planned transfers between entities. Ask how the employer handles employment certification.
- Offer comparison. Compare remaining loan payments and after-tax employment value across the positions you would realistically accept.
Keep these records together. They make it easier to distinguish an employer question from a loan-servicing question and give your financial adviser concrete inputs rather than a verbal summary.
Can residency and fellowship count toward PSLF?
120 qualifying monthly payments can include qualifying payments made during residency and fellowship. Training status itself does not disqualify you, but your employer, loans, repayment status, and payments must satisfy the applicable requirements.
Do not equate time in training with credited PSLF progress. Months in deferment or forbearance require separate review under applicable rules; they are not automatically interchangeable with qualifying repayment months.
Obtain employment certification for prior training positions and review the resulting payment record. An attending offer comparison becomes more useful when you know how much progress is already documented.
Does PSLF require another decade at the same hospital?
120 qualifying monthly payments represent a minimum of 10 years of qualifying repayment, not a requirement to stay with one hospital. Qualifying payments do not need to be consecutive, and changing qualifying employers does not erase previously credited progress.
Under Federal Student Aid's PSLF full-time standard, qualifying employment generally requires an average of at least 30 hours per week. Review the rules for multiple qualifying employers and any applicable special circumstances before reducing your schedule.
A nonqualifying job change can pause progress without cancelling prior qualifying payments. Compare the effect on your expected forgiveness date before accepting the new position.
Is PSLF forgiveness federally taxable?
120 qualifying monthly payments can lead to PSLF forgiveness that is excluded from federal income tax. PSLF's federal tax treatment is distinct from the treatment of other student-loan cancellation programs.
Confirm the state treatment that applies when forgiveness occurs. For a 2026 comparison, do not subtract an assumed federal tax bill from PSLF forgiveness or assume every form of employer loan assistance receives the same treatment.
How should you compare PSLF with a higher-paying private job?
Compare both offers over the same period, beginning today. Include the loan payments you expect to make, after-tax compensation, retirement benefits, insurance, and employment expenses that differ between the positions.
Then examine the period after expected forgiveness. A short-term advantage does not settle the value of a longer career path, particularly when partnership opportunities, workload, or geographic preferences differ.
Do not compare tax-free forgiveness directly with gross salary. Salary requires an after-tax calculation, while PSLF forgiveness requires a realistic eligibility and repayment projection. Ask a qualified adviser to check the assumptions before accepting a lower compensation package specifically to pursue forgiveness.
Private refinancing is a separate decision. Refinancing federal loans into a private loan removes those refinanced balances from federal PSLF eligibility, so resolve the PSLF comparison before making that change.
Turn the calculation into a radiology job shortlist
Use RadBoard to compare radiology job opportunities, then ask each employer the same eligibility questions. Keep verified employer information beside the compensation and schedule details rather than treating a nonprofit affiliation as a completed check.
RadBoard's radiology job search platform supports discovering opportunities; Federal Student Aid records and employer documentation support the PSLF decision. Save positions that meet your clinical priorities, and distinguish confirmed facts from questions still awaiting an answer.
FAQ
How much does PSLF save a radiologist with federal student loans?
PSLF forgives the eligible Direct Loan balance remaining after 120 qualifying monthly payments and completion of the other requirements. Your individual savings depend on future payments, interest, and the repayment alternative you compare.
Does every nonprofit hospital radiology job qualify for PSLF?
No. PSLF generally depends on your legal employer, not simply the nonprofit status of the hospital where you work. Verify the employing entity and investigate any applicable contracted-employment exception.
Can my radiology residency payments count toward PSLF?
Yes, residency payments can count when the loans, repayment, employment, and payments meet PSLF requirements. Review your recorded payment count and certify the training employment rather than counting training years automatically.
Does a high radiologist salary make me ineligible for PSLF?
A high salary alone does not disqualify a radiologist from PSLF. Higher required payments can reduce or eliminate the balance remaining for forgiveness, so project the actual repayment path.
Do I lose PSLF progress if I change hospitals?
Changing hospitals does not erase previously credited qualifying payments. Verify the new employer because nonqualifying employment can delay completion of the 120 qualifying monthly payments.
Can I refinance my federal loans and still use PSLF?
Federal loans refinanced into private student loans no longer qualify for PSLF. Compare the federal repayment path before refinancing, because a private loan cannot simply be switched back into PSLF.
Is PSLF forgiveness taxable for a radiologist?
PSLF forgiveness is excluded from federal income tax. Confirm the state tax treatment applicable when your forgiveness occurs rather than assuming all jurisdictions treat it identically.
One last thing
Your hospital badge is not proof of qualifying employment. Before you sign, match the legal employer in the contract to the entity used for PSLF verification and certification. That check belongs ahead of any forgiveness estimate in your offer comparison.